As college tuition payments approach, here’s what to consider before you access your 529 savings plan.
Navigating the Costs of College: Essential Tips for Making the Most of Your 529 Savings Plan
Category Classification: Personal Finance
Riding the Financial Waves: Navigating 529 College Savings in Uncertain Times
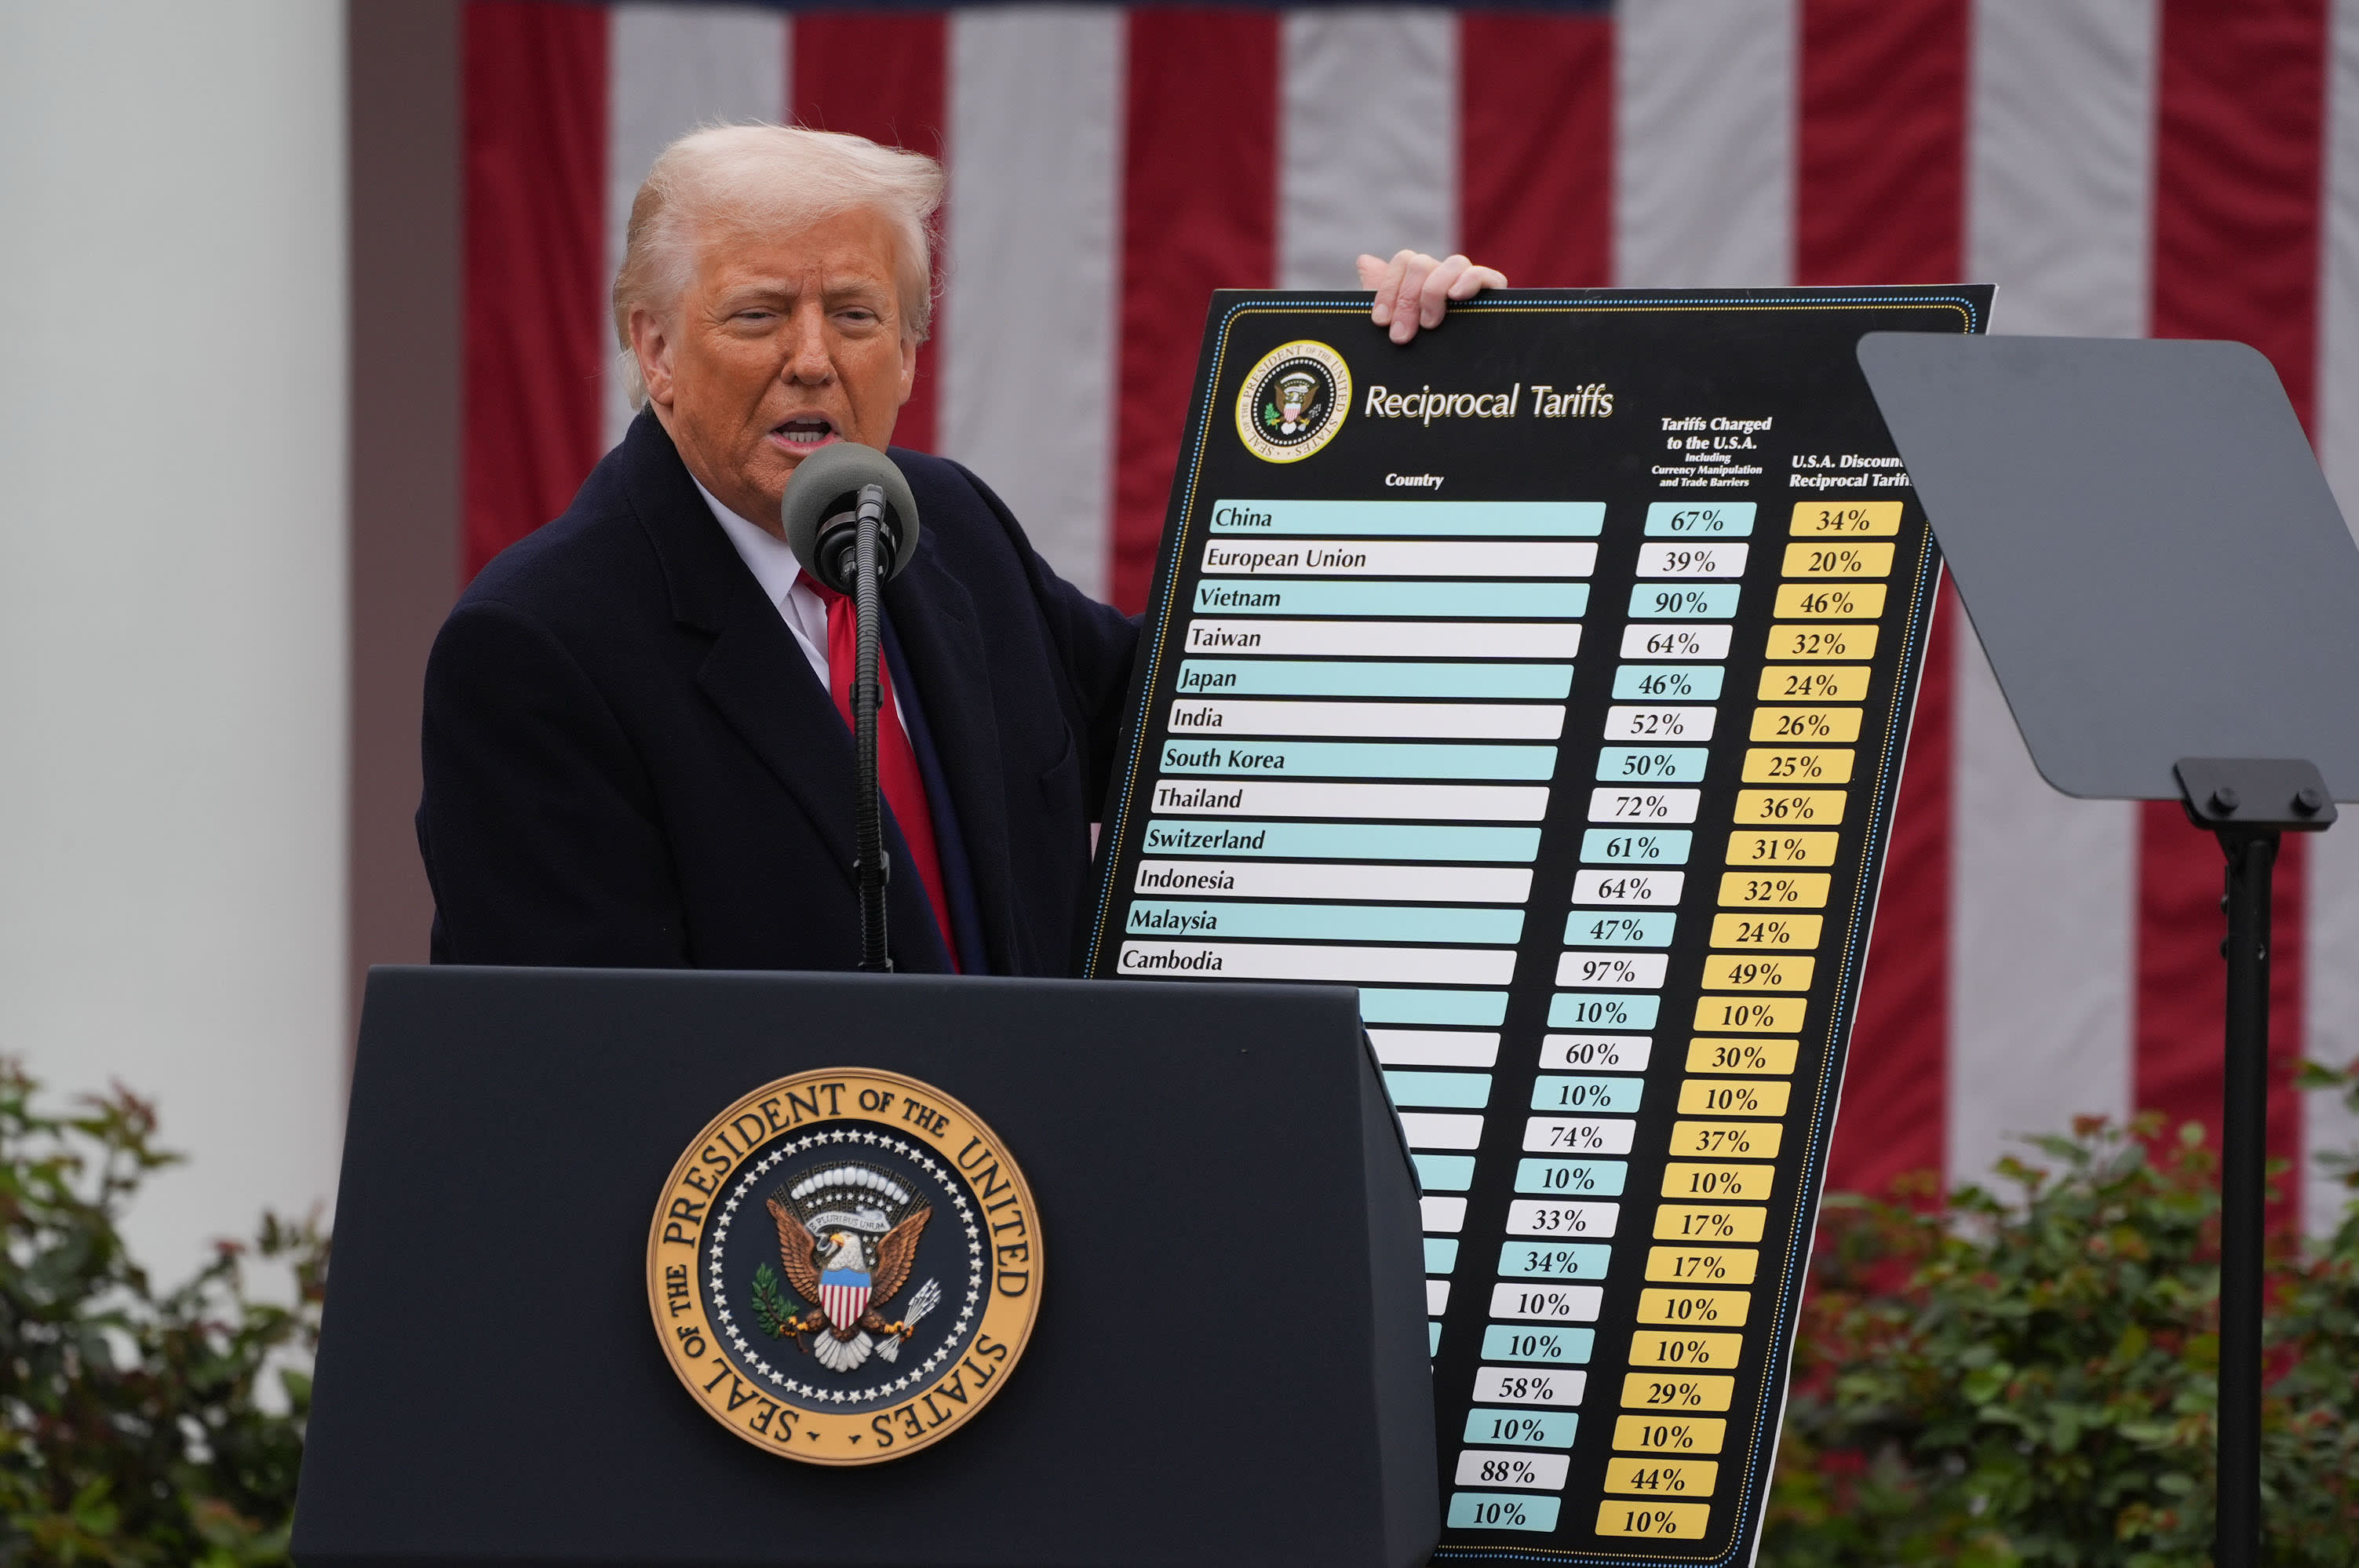
Since the onset of shifting tariff strategies spearheaded by President Donald Trump, financial markets have been akin to a thrilling amusement park ride, particularly since April. While the S&P 500 index has shown signs of recovery from its previous lows, families meticulously planning for educational expenses may discover that their 529 college savings plans haven't made a full comeback just yet.
Making the Most of Withdrawals
As tuition deadlines loom, there are several important aspects to consider before making any withdrawals. "With some thoughtful planning, tapping into these accounts can become a moment of joy rather than a cause for concern," states Smitha Walling, head of Vanguard's Education Savings Group.
Adjusting to Market Volatility
Parents feeling the pressure from their 529 accounts in these unpredictable economic times should heed the advice of Mary Morris, CEO of Commonwealth Savers. She emphasizes the importance of assessing your risk tolerance. Typically, 529 plans adapt their asset allocation over time, starting with more aggressive investments in stocks during the child's early years and gradually shifting to conservative choices as college approaches. By the time students are set to graduate high school, it's likely that families have moved a significant portion of their investments into safer assets like bonds and cash, which can safeguard against severe losses, but may also limit potential gains.
Consider Your Allocation Strategy
"If your entire portfolio is heavily invested in stocks, you might want to reconsider that approach," Morris warns. If the market's ups and downs feel overwhelming, it may be wise to change your asset allocation. Richard Polimeni, head of education savings at Merrill Lynch, suggests that one effective strategy could involve reducing your exposure to riskier investments by reallocating a part of your portfolio into cash-equivalent assets. This can help protect your principal while still yielding a competitive return and peace of mind. However, experts advise against moving your whole 529 balance into cash. "The worst mistake an investor can make during downturns is to panic and sell at a loss," cautions Polimeni.
Crafting a Smart Withdrawal Plan
For those facing immediate tuition payments, Walling advises considering whether it's more beneficial to draw from the 529 plan now or allow it to continue growing. Polimeni encourages using external income or savings to cover short-term college costs, suggesting you can later reimburse yourself from the 529 account, which allows the investment time to recover.
Moreover, families can tap into federal student loans and later utilize 529 funds to settle this debt. However, if private or personal loans with immediate interest are on the table, it might be prudent to expend 529 resources first, delaying the borrowing.
Contributions Remain Essential
Once a withdrawal strategy is established, experts stress the importance of maintaining contributions to your 529 plan. Not only might this offer tax benefits, but it also helps your investment grow in a tax-advantaged environment, whether you're contributing over 18 years or just a few short years. "The longer you remain invested, the more your savings can grow tax-deferred," highlights Polimeni.
The Evolving Landscape of College Savings
"While market fluctuations are inevitable, students' aspirations remain unwavering," remarks Chris McGee, chair of the College Savings Foundation. Despite higher education costs leading many prospective students to reassess their plans, college savings accounts are as crucial as ever.
According to a recent College Savings Foundation survey of 1,000 high school students, about 42% are shifting towards technical training or enrolling in more affordable community or in-state institutions, an increase from 37% last year. Consequently, a majority of students, around 69%, anticipate living at home while studying, the highest figure in three years.
New Advantages for 529 Plan Holders
Recent changes have further enhanced the allure of 529 plans. Starting in 2024, families will have the opportunity to roll over unused 529 funds into a Roth IRA without incurring taxes or penalties, provided specific conditions are met. Additionally, the flexibility to use 529 funds for continuing education courses, apprenticeship programs, and even student loan repayments has increased.
Growing Popularity of 529 Plans
In light of these enhancements, the appeal of 529 college savings plans continues to rise. As of 2024, the total number of 529 plan accounts surged to 17 million, reflecting an increase of over 3% from the previous year. Investments in these plans climbed to $525 billion, an 11% rise, with the average account balance reaching an unprecedented $30,961, according to the College Savings Plans Network. "The industry has experienced remarkable growth, marking the best year ever for new contributions," states Polimeni.