Three essential financial strategies to explore as the Fed maintains elevated interest rates.
Unlocking Financial Potential: Three Key Strategies to Navigate High Fed Interest Rates
Category Classification: Personal Finance
Federal Reserve Sticks to High Rates: What This Means for You
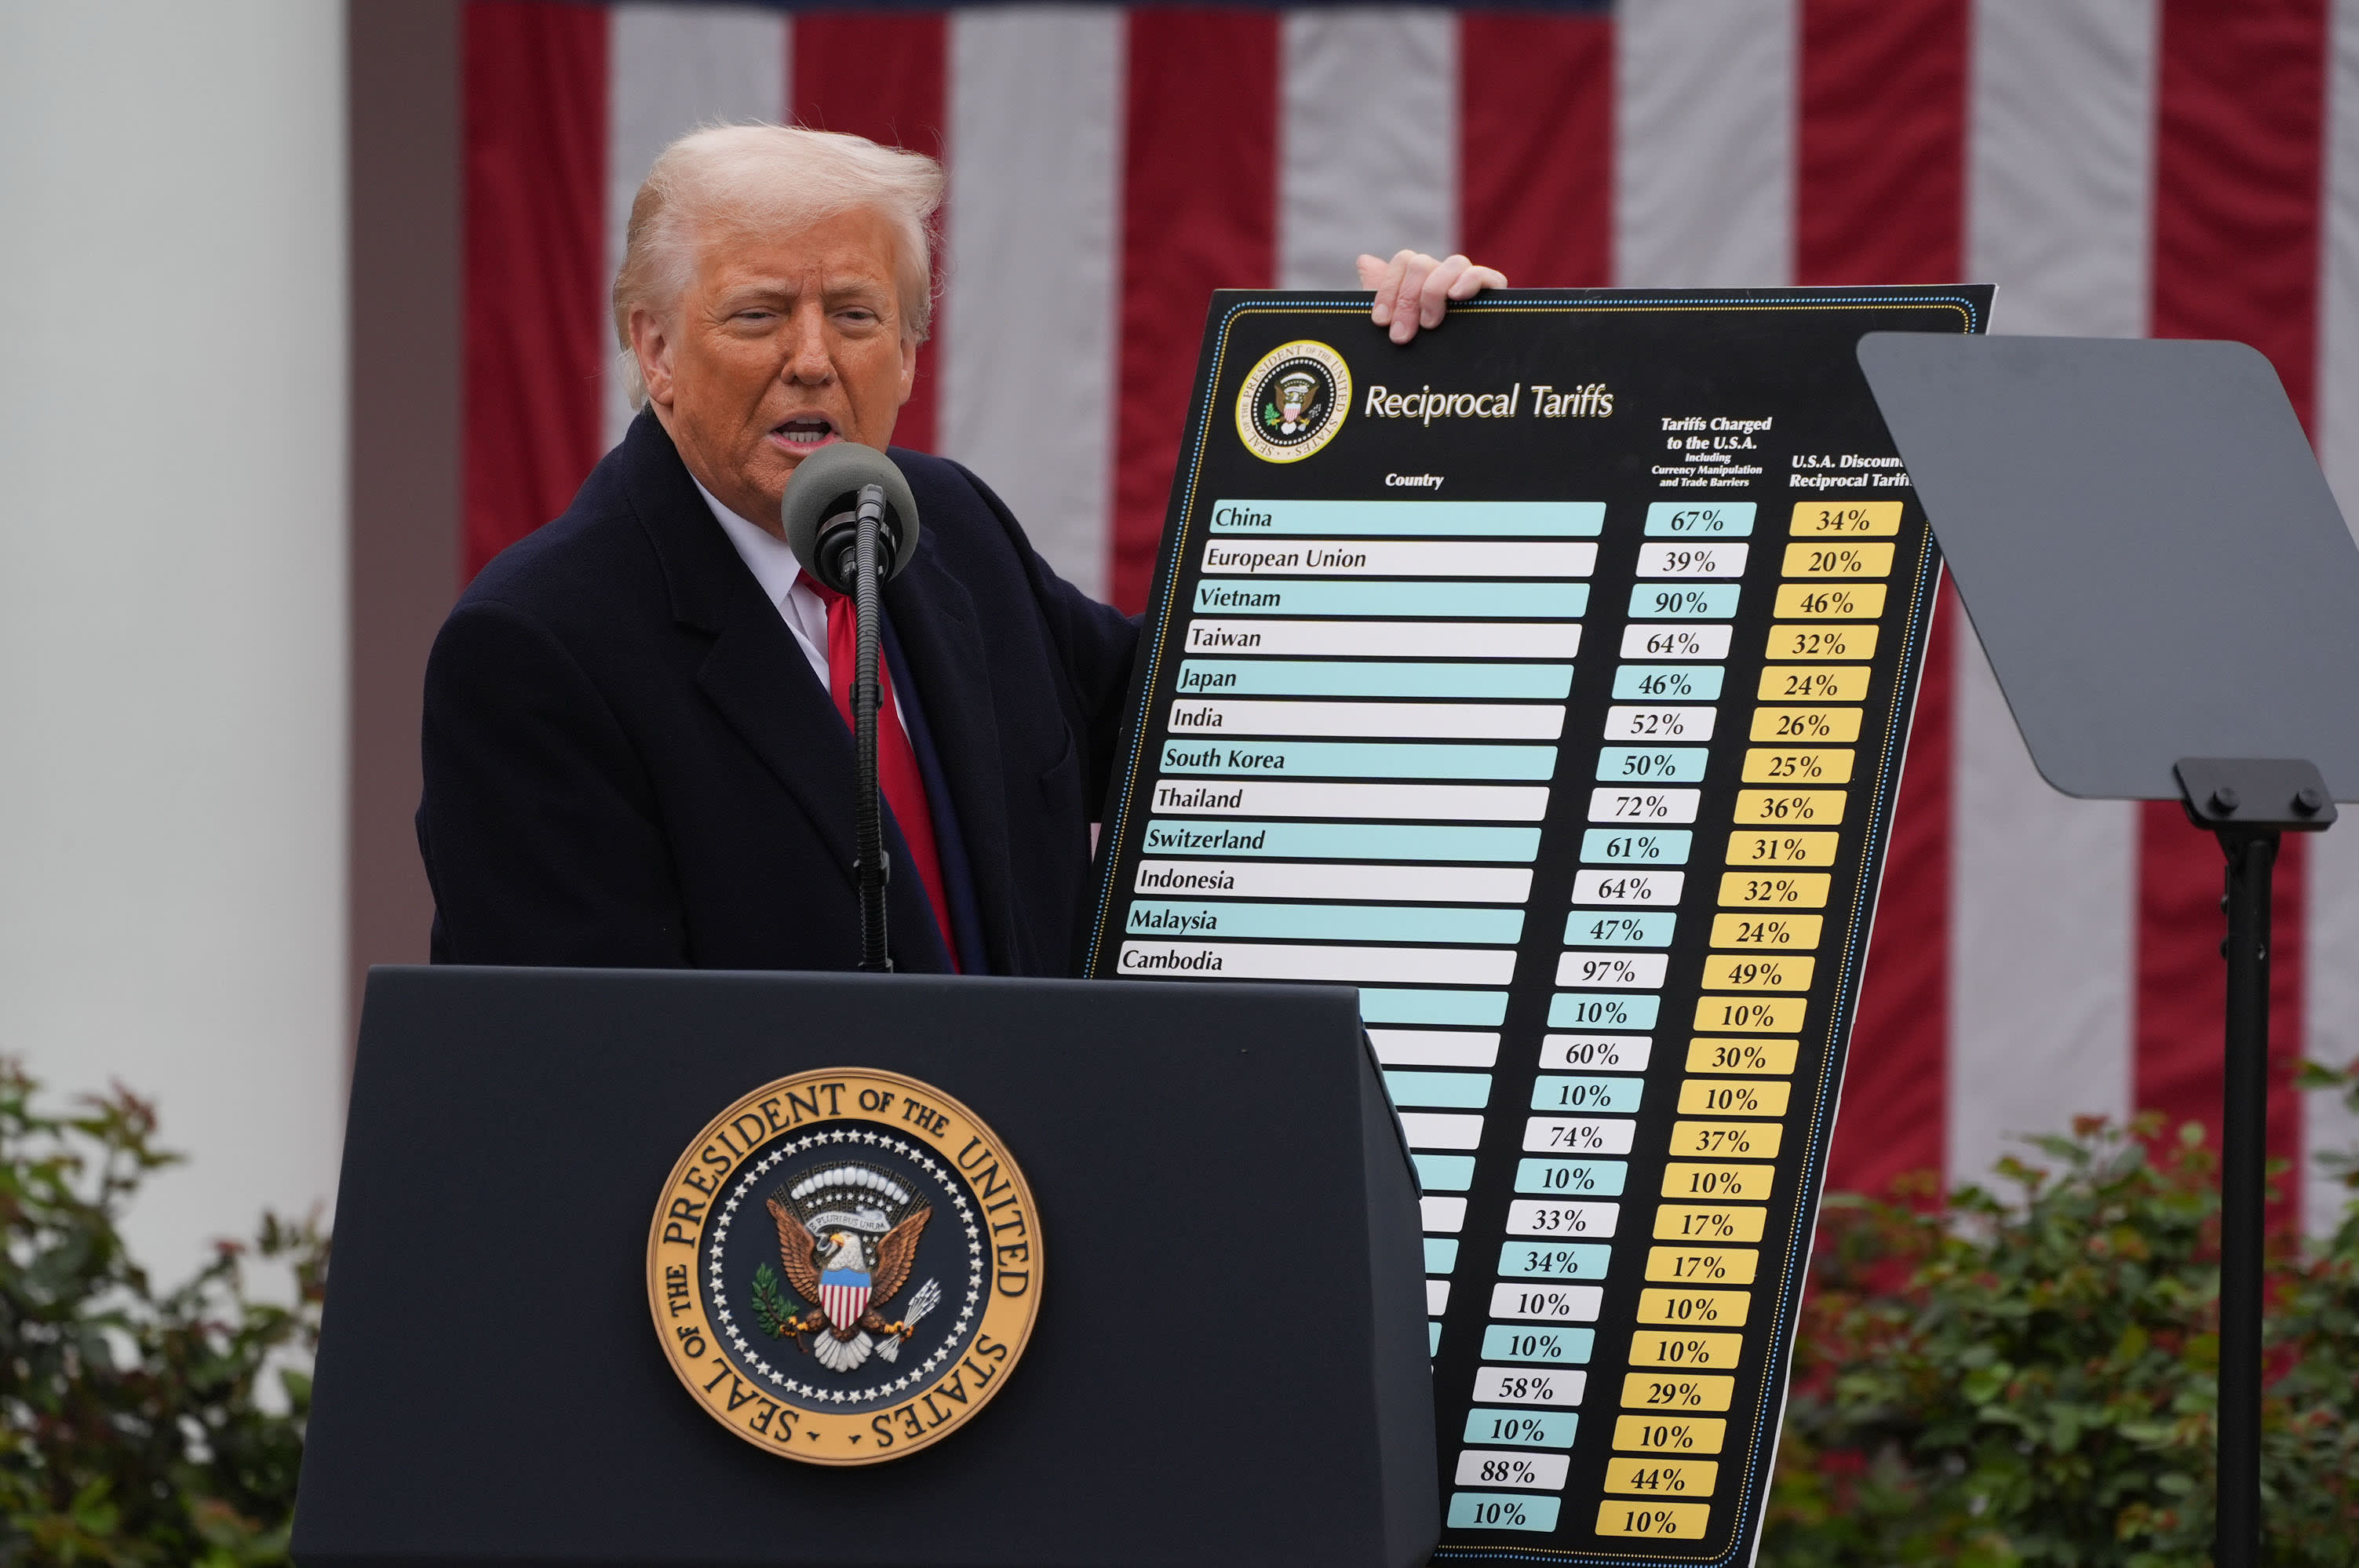
This week, the Federal Reserve shared insights from its May meeting, signaling that a drop in interest rates is not on the horizon. The central bank is holding off, awaiting clearer economic signals amid fluctuating tariff strategies. This cautious approach indicates that any decision to lower rates hinges on solid fiscal and trade policy strategies.
According to Fed Chair Jerome Powell, the federal funds rate is set to remain high as the economic landscape evolves. The benchmark plays a pivotal role in determining overnight lending costs among banks, which in turn affects the interest rates on loans and savings that everyday Americans deal with.
The Waiting Game for Rate Cuts
Currently, the federal funds rate is targeted between 4.25% and 4.5%—a range that has remained steady since December. Market predictions show almost no expectation for a rate cut at next month's Federal Open Market Committee meeting, and only a slim chance for a drop in July, as suggested by CME Group’s FedWatch tool. The earliest potential for any modification may not be until September, leaving consumers burdened by soaring prices and high borrowing costs.
“You can’t just sit back waiting for the Fed to make things easier,” mentioned Matt Schulz, Chief Credit Analyst at LendingTree. “Taking proactive steps can have a far greater impact on your finances than any rate cut.” Here are three strategies to consider:
1. Tackle Credit Card Debt
With anticipated rate reductions likely delayed until at least September, credit card interest rates have surged above 20%, nearing last year’s record highs. As banks elevated rates in 2024, the burden of credit card debt has become significantly heavier. Howard Dvorkin, a certified public accountant and chairman at Debt.com, cautions that high interest on credit cards can lead to costly financial pitfalls.
Instead of waiting for a rate cut, borrowers should explore options to manage their debt now, such as transferring balances to a zero-interest credit card or consolidating high-interest debts with a lower-rate loan. “Taking steps to reduce your interest payments can dramatically change your financial outlook,” Schulz explained. Focusing on repaying the most expensive credit cards first can further amplify savings on interest.
2. Secure a High-Yield Savings Account
Anticipation of a rate cut means that the current rates for online savings accounts, money markets, and CDs are also expected to decrease. Now is a prime time to secure a higher return, especially with a high-yield savings account offering competitive rates around 4.5%—still a solid return compared to historical trends.
For instance, a saver with $10,000 could potentially earn an extra $450 annually by shifting to a high-yield account versus a traditional one yielding around 0.42%. Schulz warns that sticking with a major bank’s standard savings account may result in missed opportunities for better returns.
3. Boost Your Credit Score
A promising credit score can unlock lower interest rates on loans. Generally, a higher score means more favorable access and loan terms, while lower scores can result in elevated borrowing costs. However, recent trends show a decline in average credit scores, partly due to pressures from rising debt and resumed federal student loan reporting.
To enhance your credit score, prioritize timely bill payments and keep your credit utilization below 30%. Tommy Lee, senior director at FICO, emphasizes that even modest improvements in your score can yield substantial long-term savings, with lower mortgage rates and better conditions for personal loans being the most beneficial.
Improving your credit score from fair to very good can save you over $39,000 throughout the lifetime of your balances, demonstrating the importance of taking proactive financial steps today.